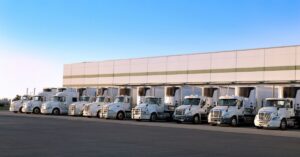
7-Eleven Inc. is considering bringing parts of its North American supply chain back in-house.
Reuters reported on Oct. 9 that new 7-Eleven Inc. CEO Mauricio Leyva said the company is reviewing further cost reductions and reshaping its sourcing and distribution network. Seven & i Holdings CEO Stephen Dacus said in the same interview, “To a certain extent we’ve outsourced too much.”
The review is about control, not just cuts
Outsourcing can lower capital needs and tap third-party scale. It can also leave retailers exposed when fuel, freight, vendor and service costs rise together. 7-Eleven’s comments suggest the company is testing where direct capability could lower costs or improve execution, rather than simply renegotiating vendor fees.
That distinction matters because 7-Eleven is trying to shift more of its North American offer toward fresh food, proprietary products, delivery and improved store formats. Those areas depend on tight supply-chain execution, not only shelf-price decisions.
Cost pressure is showing up across the business
Seven & i’s Oct. 8 fiscal second-quarter update showed progress in North America, even as inflation, supplier costs and fuel expenses pressure shoppers and margins. 7-Eleven Inc., also known as SEI in Seven & i materials, reported U.S. same-store merchandise sales growth of 0.6% for the first half, while merchandise gross profit margin improved 0.3 percentage points to 33.5%. 7NOW sales rose 15.6% year over year to US$550 million, and operating income increased 45.8% to US$1.32 billion.
Fuel is a two-sided factor. Seven & i said favorable fuel market conditions and progress in vertical integration contributed to SEI’s income growth. The same update said SG&A expenses stayed within plan despite higher credit-card fees tied to increased fuel prices, while its consolidated results said U.S. same-store sales slightly declined in the second quarter as lower customer traffic was driven largely by persistently high fuel prices.
The filing also listed fluctuations in raw materials, merchandise, logistics and labor costs among the risks that could affect results. That makes supply-chain ownership a financial question as much as an operating one.
The supply-chain review started before the latest interview
In an April investor Q&A, Seven & i said it was taking a hard look at the U.S. supply chain as part of its transformation plan and was studying how to drive better efficiency and value. The company said it had put new projects on hold, including the Ohio Commissary, while reviewing how those projects fit with future plans.
Seven & i also said Warabeya Nichiyo remained an important global partner. That caveat keeps the latest comments from reading as a blanket rejection of suppliers.
What remains unclear
7-Eleven has not announced a formal restructuring, identified affected vendors or set a timeline. The review could touch sourcing, distribution, commissary projects, transport, fuel logistics or supporting technology, but the company has not confirmed any specific targets.
7-Eleven’s public vendor/supplier guidelines show how broad the network can be. The company defines authorized distributors to include wholesalers, exporters, commissaries, bakeries, combined distribution centers and associated distribution centers. Those guidelines do not identify what may change, but they show that any supply-chain redesign could involve several types of partners.
The decision reaches beyond 7-Eleven
For vendors and logistics providers, more internal capability could affect volume, contract structure and margin. For franchisees and store operators, the question is whether any savings or control translate into better availability, stronger food execution, lower waste, better value offers or improved store economics.
For the broader retail market, the development shows how outsourcing math changes when fuel volatility, supplier pass-throughs, service expectations and data systems all have to be managed together. Retailers with enough scale may decide the cost of control is lower than the cost of coordination.
What to watch next
The next useful disclosures would answer four questions:
- Which functions 7-Eleven wants to own directly.
- How much capital the company would commit and over what payback period.
- How suppliers, distributors and franchisees would be affected.
- Whether cost savings would support margins, store-level economics or consumer value offers.
The timing also connects to Seven & i’s postponed North American IPO plan. In April, the company said the listing target had moved to 2027 at the earliest. Reuters reported that Dacus said a future IPO would depend on the macro environment and on giving investors more evidence that the turnaround is working.
I can suggest related Tech Help Canada articles based on the topic you’re reading now.
Tech Help Canada Staff researches, writes, and reviews practical content for business owners and professionals. Our coverage spans business, marketing, SEO, technology, and the tools and systems people use to grow and operate online. We focus on clear, useful information backed by research, hands-on experience, and editorial review. Learn more about our team and editorial standards. Need help with something? Contact Us