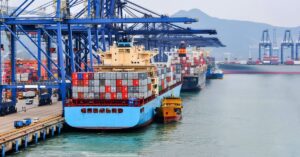
U.S.-bound freight demand is still holding even as key transpacific spot rates remain expensive.
The latest Descartes Global Shipping Report said U.S. containerized imports reached 2,546,261 TEUs in September 2026. That was down 2.2% from August, but up 10.3% from September 2025 and the highest September volume on record. Descartes said September volumes were also 24.8% above September 2019.
Descartes reported that China-origin imports reached 924,454 TEUs in September, up 4.5% from August and 21.2% from September 2025. China accounted for 36.3% of total U.S. container imports in the month, up from 34.0% in August.
The report also showed that the top 10 countries of origin were nearly unchanged from August as a group, but were 13.1% above September 2025. China provided most of that annual gain.
That strength did not remove operational pressure. Descartes said port transit delays increased at eight of the top 10 U.S. gateways in September. New York/New Jersey had the largest increase, rising 1.5 days to 8.3 days, while Houston rose 1.4 days to 7.2 days.
For North American businesses that depend on imported electronics, hardware, components, retail inventory or ecommerce goods, the data suggests a market where freight demand is still strong enough to keep pressure on routing, port operations and landed-cost planning.
Rates are easing, but not everywhere
Drewry’s World Container Index fell 2% to $4,351 per 40-foot container in its Oct. 8 assessment. Drewry attributed the decline to lower rates on transpacific and Asia-Europe routes as demand weakened during China’s Golden Week.
Even after the pullback, transpacific rates remained high. Drewry said Shanghai-to-Los Angeles rates fell 3% to $7,624 per 40-foot container, while Shanghai-to-New York rates declined 2% to $10,220.
Freightos reported a similar split in its Oct. 6 update. Its weekly Freightos Baltic Index readings showed Asia-U.S. West Coast prices down 1% and Asia-U.S. East Coast prices flat. Freightos also reported transpacific container rates at $8,322 per FEU to the West Coast and $9,600 per FEU to the East Coast, with increased blank sailings around Golden Week helping support prices in the near term.
A short-term drop in spot rates does not necessarily signal weak freight demand when rates remain elevated and capacity is still being actively managed.
Asia-Europe looks weaker than the transpacific
The Asia-Europe trade is showing clearer rate pressure. Drewry said Shanghai-to-Rotterdam rates fell 2% to $3,337 per 40-foot container, while Shanghai-to-Genoa rates remained stable at $3,696. Drewry added that Asia-Europe rates have declined for 13 consecutive weeks.
Freightos tied part of that weakness to more carriers returning to the Red Sea and Suez Canal route, which shortens voyages and increases effective capacity. Freightos said Asia-North Europe prices dipped to $3,260 per FEU and Asia-Mediterranean prices to $3,555 per FEU in the prior week.
Lloyd’s List reported on Oct. 7 that Suez container transits reached 314 in September, up 64% year over year and the highest level since the Houthi attacks began. It also reported that about 35% of Asia-Europe sailings were using the Red Sea, putting rates under pressure as capacity returns.
Retail and carrier data point to firm demand
The National Retail Federation and Hackett Associates said in their Oct. 8 Global Port Tracker update that the extended U.S. peak shipping season appears to be winding down after remaining elevated through the summer and early fall. NRF projected September import volume at 2.28 million TEU, up 8.2% year over year, after August reached 2.3 million TEU and was likely the busiest month of 2026.
NRF forecast October at 2.25 million TEU, up 8.5% year over year. Hackett Associates said consumer spending remained robust despite weakening confidence and increasing inflation, while NRF said most holiday merchandise had already arrived and the remainder of the year would be driven more by replenishment and preparation for early 2027.
Carrier data points in the same direction. Orient Overseas International’s unaudited operational update for the second quarter of 2026 showed OOCL liner revenue up 19.8% year over year to US$2.537 billion, while total liftings rose 8.8%. Trans-Pacific liftings increased 21.5% from the same quarter in 2025.
For the first half of 2026, OOCL liftings rose 5.2% and liner revenue rose 5.5% year over year. In its interim results released in August, OOIL said OOCL recorded its highest first-half liftings and liner revenue outside the pandemic period.
Freight planning needs a lane-by-lane view
For companies exposed to ocean freight, broad averages can mislead. The practical cost picture depends on lane, origin, port choice, sailing reliability, fuel charges, tariff exposure and timing around holiday periods.
Drewry expects rates to remain stable next week, but also said the market is likely to remain volatile in the near term as demand, capacity changes and geopolitical developments continue to influence freight rates.
Get new small business insights by email
Practical ideas and useful articles to help you make better business decisions.
Tech Help Canada Staff researches, writes, and reviews practical content for business owners and professionals. Our coverage spans business, marketing, SEO, technology, and the tools and systems people use to grow and operate online. We focus on clear, useful information backed by research, hands-on experience, and editorial review. Learn more about our team and editorial standards. Need help with something? Contact Us